What is a credit note?
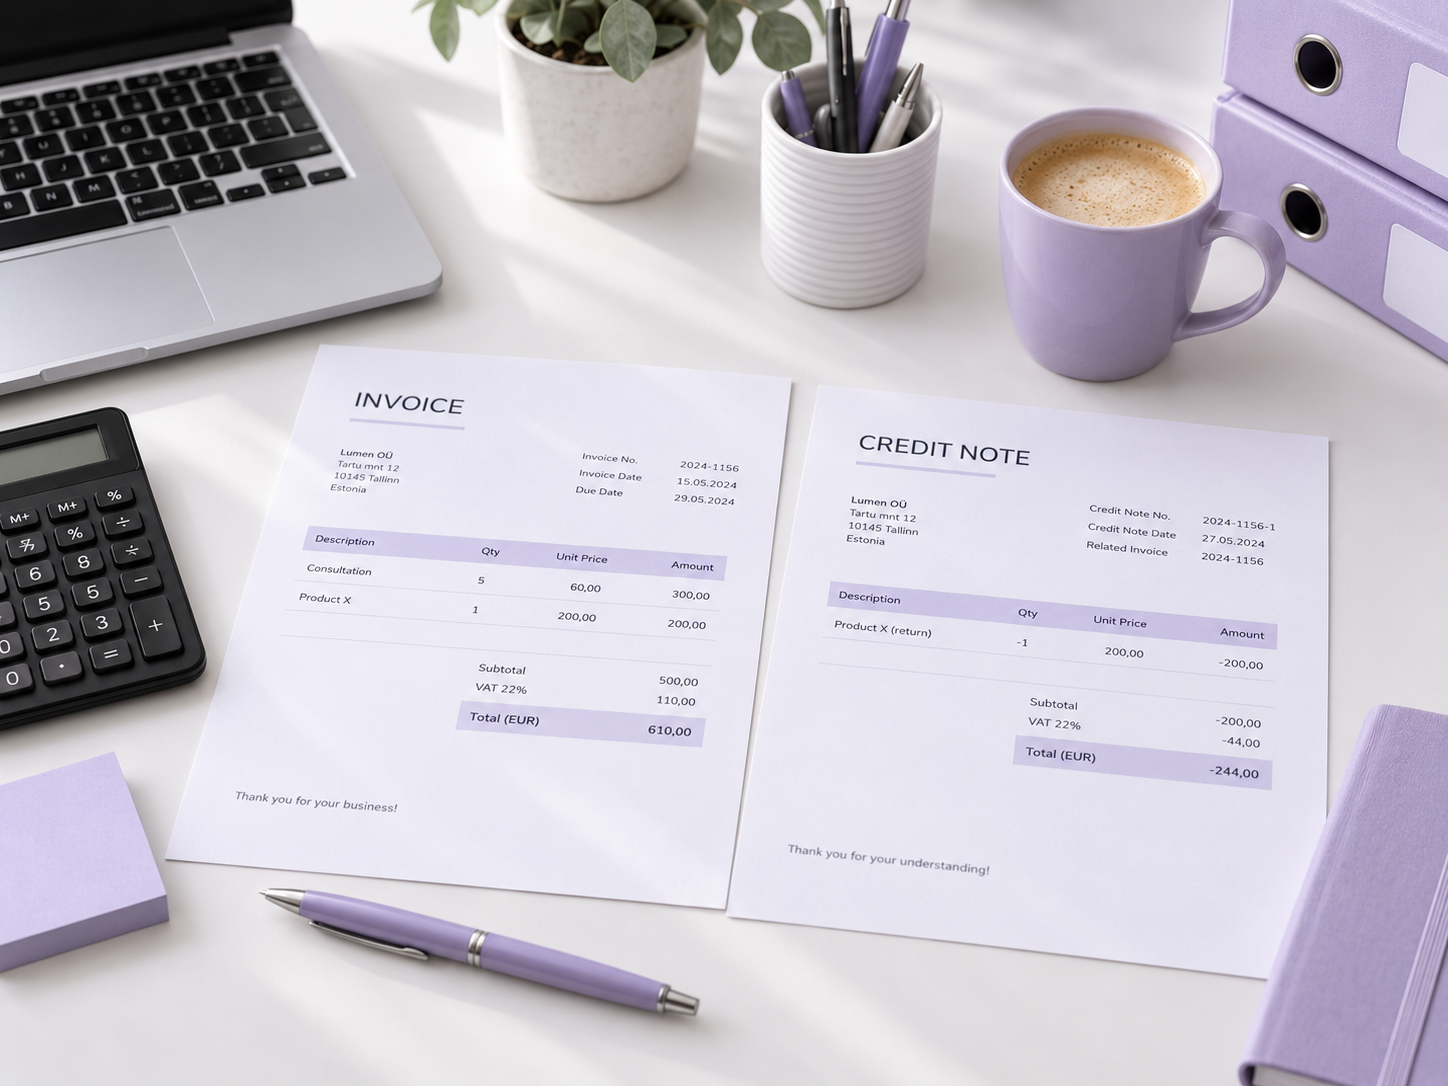
A credit note is a document that reduces the amount of an earlier invoice or cancels it entirely. In Estonian business practice you may also see the term kreeditarve. The key point is that the document must be linked to a specific original invoice.
A credit note does not erase the original invoice. The original invoice and the related credit note remain in the records together, so the correction can be followed later by management, accountants and the Tax and Customs Board.
When should you issue a credit note?
- the customer returns goods;
- the order or service is cancelled;
- the price is reduced after the invoice was issued;
- the original invoice contains the wrong quantity, price or amount;
- a later discount is granted;
- part of the invoiced work was not completed;
- the original invoice needs to be cancelled in full.
In practice there are two common versions: a full credit note, which reverses the whole invoice, and a partial credit note, which reduces only the specific line, quantity or amount that needs correction.
What information should the document include?
- the document title, for example Credit Note or Kreeditarve;
- a unique document number and the issue date;
- the seller’s name, address, registry code and, where relevant, VAT number;
- the customer’s name and address;
- the number of the original invoice and ideally its date;
- the reason for the correction;
- the description, quantity and price of the goods or services being reduced;
- the taxable amount, VAT rate and VAT amount;
- the total amount of the credit note.
Example credit note
| Field | Example |
|---|---|
| Document | Credit Note CN-2026-004 |
| Issue date | 18.09.2026 |
| Original invoice | Invoice No. 2026-118 dated 10.09.2026 |
| Seller | Example Company OÜ · registry code 12345678 · VAT No. EE123456789 |
| Customer | Client Company OÜ · registry code 87654321 |
| Reason | Reduction in the scope of the service |
| Corrected line | Website maintenance service, quantity -1, net amount -100.00 € |
| VAT | 24% VAT: -24.00 € |
| Total credit note | -124.00 € |
If the original invoice has already been paid, the seller will usually need to refund the corresponding amount to the customer, unless both parties agree to keep it as an advance payment for a later invoice.
How to create a credit note in Arveteha
In Arveteha, the most logical way to create a credit note is from the original sales invoice. This keeps the relationship between the two documents intact and makes it clear in the PDF which earlier invoice is being corrected.
- Open the Arveteha cabinet and go to Arved / Invoices in the left-hand menu.
- Find the original invoice that needs to be reduced or cancelled.
- Open the invoice view or edit page.
- From the actions menu choose Create credit note.
- The system should carry over the seller, customer, invoice lines and reference to the original invoice.
- Decide whether you need a full credit note or a partial credit note.
- If the whole invoice must be reversed, keep all lines negative or reduce the full total.
- If only part of the invoice changes, adjust only the relevant line or amount.
- Add a short explanation such as goods return, service reduction or price correction.
- Save the document, review the figures, confirm it and download the PDF.
Which VAT rate should you use?
A credit note corrects the transaction shown on the original invoice. That is why the credit note should generally use the same VAT rate as the original invoice, rather than simply the rate in force on the date of the correction.
For example, if the original invoice used a 20%, 22% or 24% VAT rate, the credit note linked to that invoice should normally reflect the same rate for the corrected amount. Estonia’s standard VAT rate is 24% from 1 July 2025, but older invoices may still have been issued using earlier rates.
According to MTA guidance for the KMD INF form, credit note values are usually reported with a minus sign, and earlier VAT rates can still matter depending on the original transaction.
How is it reflected in accounting and VAT reporting?
If the VAT return for the original transaction period has already been filed, the seller and the buyer usually reflect the change connected to the cancelled transaction or reduced price in the tax period when the credit note is issued.
| Situation | Usual action |
|---|---|
| The whole transaction is cancelled | Issue a full credit note and keep the original invoice in the records. |
| Only the price or quantity is reduced | Issue a partial credit note for the reduced part only. |
| The original invoice was entirely wrong | Credit it in full and, if needed, issue a new correct invoice. |
| The customer simply does not pay | Do not cancel the transaction automatically; check the separate bad-debt VAT rules. |
The document should always be tied to a specific original invoice. In VAT reporting, the numerical data of the credit note is typically shown with minus values.
Common mistakes when issuing a credit note
- not referring to the original invoice;
- reusing the original invoice number;
- applying the wrong VAT rate;
- failing to show the reduced amounts clearly as negative;
- not stating the reason for the correction;
- deleting the original invoice and losing the document trail.
Frequently asked questions
Below are the questions businesses ask most often when they need to correct an earlier invoice.
Official sources
- Estonian Tax and Customs Board (MTA): information included in invoices
- MTA: VAT accounting and invoices
- MTA: standard VAT rate
- Value-Added Tax Act (English translation)
This article is for general information. For a complex real-life correction, especially where returns, partial deliveries or filed VAT returns are involved, it is sensible to confirm the treatment with an accountant or tax adviser.
Can I issue a credit note without an original invoice?
No. A credit note should be linked to a specific invoice that was issued earlier. Without that reference, the correction is not properly documented.
Does a credit note always show negative amounts?
Its purpose is to reduce a previous invoice, so in practice the corrected amounts are normally shown as negative. This also makes the effect clear in accounting and VAT reporting.
What if I need to increase the amount instead of reducing it?
If the amount needs to be increased, businesses usually issue a new or supplementary invoice. A credit note is meant for reducing an earlier claim, not increasing it.
Can a credit note be sent as a PDF?
Yes. A credit note may be electronic as long as it remains readable, storable and clearly linked to the original invoice it corrects.
Do I always need to issue a new invoice after a credit note?
Not always. A new invoice is usually needed when the original invoice was fully credited and the transaction must be invoiced again with the correct data. For a partial correction, the credit note alone may be enough.
Which VAT rate should the credit note use?
As a rule, the credit note should follow the VAT rate used on the original invoice. It corrects that earlier transaction, so the original VAT treatment matters.
Official sources
- MTA: information included in invoices
- MTA: VAT accounting and invoices
- MTA: standard VAT rate
- Value-Added Tax Act (English translation)
This material is for general information. If a specific transaction is complex, cross-border or already declared, confirm the tax treatment with an accountant or tax adviser.